Have you ever considered an insurance policy’s actual internal rate of return? If you do the math and calculate the potential tax-free rate of return on term-to-age-100 term life insurance policies, you quickly learn that a death benefit can be an effective estate-planning tool. To hypothetically illustrate this further, consider John, a healthy 60-year-old male (non-smoker) who purchased a $500,000 life insurance policy.
John owns a business and investments that will create a tax liability of about $500,000 upon his death. He wanted to buy life insurance but was unsure whether to invest the money or pay insurance premiums. To make his decision, John would have to pay an annual premium of about $10,000 for life insurance. If John is expected to live to age 85, he would pay premiums for about 20 years, totaling $200,000.
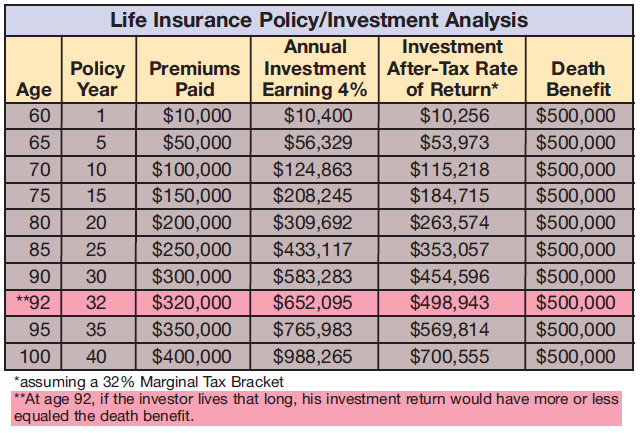
If John invested $10,000 each year in fixed-income GICs and earned 4%, he would have $309,000 at the end of 20 years (assuming no tax on accrued interest during the 20 years). If he considers the effect of annual taxes on his interest, he would have $263,574 (assuming a 36% Marginal Tax Rate). One major advantage to the life insurance proceeds is that they are tax-free! 1
When John then considers the net effect of paying insurance premiums or investing the money, he realizes that the net after-tax return on his life insurance policy is 7.37%. When he compares this to the net after-tax return of 2.56% on his fixed income investment, the answer is simple! His estate and heirs will benefit much more if he purchases a life insurance policy. The only question that John still has is what if he lives longer than 20 years? Using the chart below, John can compare the net cost at various ages.
In conclusion, John’s decision depends on his estate-planning goals and objectives. If John lives past age 92, he would have been better off making an investment.
Considering that those actuarial statistics indicate that a current 60-year-old male will only live to age 79 (Canada), John may want to consider the life insurance scenario. That would maximize the estate benefit and minimize taxation in the year of his death, as the life insurance policy would provide maximum benefit for pennies on the dollar.
From an estate planning perspective, the risk of early death is mitigated. His estate would be paid the entire guaranteed $500,000 even if he were to die one day after buying the policy.
Notes. A comparative study is needed in each case, as life insurance premiums can change and vary by company depending on the client’s health and age. Thus the policy studied is not mentioned. Tax-free status can change depending on legislation and method of premium payment.
Graph: AdviceonMedia